• Skip to main content
  • Skip to footer

Jim Wyckoff

Dominate Your Market

  • Daily Morning Report
  • Meet Jim
    • Testimonials
  • Contact Jim
  • Sample Reports and Charts
  • FAQ
  • Jim’s educational e-books

Daily Morning Report

Renewed U.S.-China tensions upset global marketplace

May 4, 2020 by Jim Wyckoff

Monday, May 4–Jim Wyckoff’s Morning Markets Report

Global stock markets were mostly down in overnight trading. U.S. stock indexes are pointed toward lower openings when the New York day session begins. On the front burner of the market place this week remains the Covid-19 pandemic and its destructive impact on the global economy. Purchasing managers’ surveys from around the world, released Friday and Monday, show unprecedented contraction in that important sector of economies during the month of April.

Said one market analyst in a morning email dispatch Monday: “The next two to three weeks are going to be extremely critical on two fronts: health and the economy. No one knows with a high degree of certainty how the Covid-19 curve will play out. While we all hope it slopes downward. There is no guarantee it will, especially with lockdown periods coming to an end. If cases begin to grow and the curve steepens, the chances are high of returning to another phase of complete shutdown. That would put economies on freeze again and the only direction for stocks to head then is down. The other risk factor is a new trade war between the U.S. and China, which is the last thing investors want to hear at this stage.”

The U.S. is ratcheting up its rhetoric blaming China for delaying reporting of the coronavirus outbreak in its early stages, and even implying the virus could have come from a Wuhan laboratory. This escalation in U.S.-China tensions could thwart the partial trade agreement the world’s two largest economies reached in January. President Trump has threatened new trade tariffs and other sanctions could be levied against China. Gold prices are rallying Monday, likely on concerns about future U.S.-China relations.

The European Central Bank on Monday forecast sharply lower economic growth and inflation for the bloc in 2020. The ECB sees Euro zone GDP down 5.5% and inflation at 0.4% in 2020. The ECB in January forecast inflation at 1.2% in 2020.

The important outside markets see Nymex crude oil prices lower lower and trading around $18.35 a barrel in June futures. The U.S. dollar index is higher today after the greenback bulls faded badly last week. The 10-year U.S. Treasury note yield is trading around 0.6% this morning.

U.S. economic reports out Monday include the ISM New York report on business, manufacturers’ shipments and inventories and the global manufacturing PMI.

–Jim
Continue Reading
Filed Under: Blog News, Jim's Morning Report, Uncategorized

U.S. stock indexes trending higher

May 1, 2020 by Jim Wyckoff

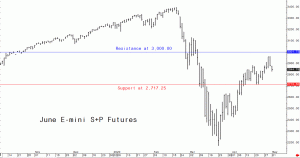
The U.S. stock indexes just finished one of their best months ever in April–despite the U.S. economy suffering historic damage from the Covid-19 pandemic shutting down commerce. See on the daily bar chart that the June e-mini S&P futures are trending higher and this week hit a seven-week high. “The trend is your friend” in trading markets, and the path of least resistance for the U.S. stock indexes remains sideways to higher as the month of May gets under way.–Stay tuned! Jim

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Downbeat trader/investor attitudes to end the week, start the month

May 1, 2020 by Jim Wyckoff

Friday, May 1–Jim Wyckoff’s Morning Markets Report

Global stock markets were mostly down in overnight trading. U.S. stock indexes are pointed toward lower openings when the New York day session begins. On this last trading day of the week and first day of the month, the past few days’ grim economic data and corporate earnings reports may be driving home to traders and investors the reality of the Covid-19-induced damage being inflicted on the global economy. Still, despite 30 million Americans losing their jobs the past few weeks, the U.S. stock indexes just finished one of their best months ever and are in near-term price uptrends on the daily charts. Some U.S. states are starting to partially reopen their businesses today.

U.S. President Trump is ramping up his negative rhetoric toward China and on Thursday again suggested China suppressed Covid-19 information in the early stages in China, even hinting China may have purposely unleased the virus from a laboratory. Trump also threatened more tariffs against China.

In other news, the European Central Bank said on Friday Euro zone economic growth could decline by 12% in 2020.

In the background and not yet impacting markets, but worth mentioning, is the extended absence in public of North Korea’s leader Kim Jong Un. In normal times this matter might get paid more attention by the marketplace.

The important outside markets see Nymex crude oil lower and trading around $18.35 a barrel in June futures. The oil market has made a strong rebound this week after the June contract hit a low of just above $10.00 on Tuesday. The U.S. dollar index is slightly weaker again today. The greenback bulls have faded badly this week. The 10-year U.S. Treasury note yield is trading around 0.6% this morning.

U.S. economic reports out today include the U.S. manufacturing purchasing managers index (PMI), the ISM manufacturing report on business, construction spending and auto industry sales.

–Jim
Continue Reading

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Traders and investors have better risk appetite as April ends

April 30, 2020 by Jim Wyckoff

Thursday, April 30–Jim Wyckoff’s Morning Markets Report

Global stock markets were mostly firmer in overnight trading, while the U.S. stock indexes are pointed toward modestly higher openings when the New York day session begins. Some upbeat news Wednesday on a drug trial that lessens the effects of Covid-19 and a big rebound in crude oil prices are prompting better trader and investor risk appetite as April winds down today. Many U.S. states are now partially reopening their businesses.

In overnight news, the Euro zone economy contracted by 3.8% in the first quarter from the fourth quarter of 2019, and was down 14.4%, year-on-year. Those numbers are a record for the 14-nation bloc. The year-on-year decline in Euro zone GDP was much greater than the 4.8% drop in U.S. GDP in the same period, and reported on Wednesday.

A Reuters (Refinitiv) survey just released shows global jewelry fabrication volumes, which typically account for around 55% of total physical demand for gold, fell 40% in the first quarter, year-on-year. Investment demand was mixed, with retail investment, which consists of bars and coins, posting an 11% year-on-year drop. Physical gold demand fell to 753 metric tons in the first quarter, the lowest levels since 2009 as higher gold prices led to a drop in consumption. The biggest declines were recorded in Asia at down over 43% year-on-year. Chinese demand recorded a 62% decline in jewelry fabrication in the period.

The important outside markets see Nymex crude oil again sharply higher and trading around $17.50 a barrel. The U.S. dollar index is slightly weaker again today. The greenback bulls are fading this week, partly on notions other major countries’ economies are coming back to life faster than that of the U.S. The 10-year U.S. Treasury note yield is trading around 0.6% this morning.

U.S. economic reports due for release Thursday include the weekly jobless claims report, which has become the focal point of the marketplace in recent weeks. This week’s jobless number is forecast to be 3.5 million in new claims. Other reports out today include personal income and outlays, the employment cost index, and the ISM Chicago business survey.

–Jim
Continue Reading

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Greenback bulls fade a bit

April 29, 2020 by Jim Wyckoff

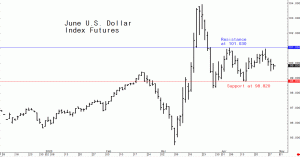
The U.S. dollar index is a basket of six major world currencies weighted against the greenback. See on the daily bar chart for the USDX futures that a price uptrend has rolled over into sideways and choppy trading. The bulls still have the overall near-term technical advantage. The direction in which prices push above or below the resistance or support line seen on the chart will likely be the next trending move for the USDX.–Stay tuned! Jim

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Major U.S. economic data points at mid-week

April 29, 2020 by Jim Wyckoff

Wednesday, April 29–Jim Wyckoff’s Morning Markets Report

Global stock markets were mixed in overnight trading, while the U.S. stock indexes are pointed toward higher openings when the New York day session begins. It’s a big day for U.S. economic data Wednesday, as the Federal Reserve’s Open Market Committee (FOMC) concludes its two-day meeting in the afternoon with a statement on U.S. monetary policy. No changes are expected but traders will parse the statement as well as Fed Chairman Jerome Powell’s virtual press conference. Powell is expected to say the Fed “will do what it takes” to get the U.S. economy back on track. Also, the advance estimate for first-quarter U.S. gross domestic product is out and is expected to show economic growth of around -4.0%. That’s a bad number but most agree the figure for the second quarter will be much worse.

In overnight news, a Hong Kong economic official said that city-state’s economy will contract between 4-7% in 2020. Reports said mainland China will hold its annual people’s conference later in May, as a show of how that country is emerging quickly from the effects of the Covid-19 pandemic. That major conference was postponed earlier this year.

The important outside markets see Nymex crude oil sharply higher and trading around $14.25 a barrel. There is talk Nymex crude prices will again fall into negative territory when the June contract nears expiration in late May. The U.S. dollar index is weaker again today. The greenback bulls are fading this week, partly on notions other major countries’ economies are coming back to life faster than that of the U.S. The 10-year U.S. Treasury note yield is trading around 0.59% this morning—down from levels seen earlier this week.

Other U.S. economic reports due for release Wednesday include the weekly MBA mortgage applications survey, the consumer price index, pending home sales, and the weekly DOE liquid energy stocks report.

–Jim
Continue Reading

Filed Under: Blog News, Jim's Morning Report, Uncategorized

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 245
  • Page 246
  • Page 247
  • Page 248
  • Page 249
  • Interim pages omitted …
  • Page 424
  • Go to Next Page »

Footer

Disclaimer

There is a risk of financial loss in futures and options trading. Futures trading is neither easy nor an easy way to make money. It takes hard work to have success. Please use sound money management when trading futures. Past performance is not necessarily indicative of future results. Nothing on this website is intended to be a trading recommendation to buy or sell futures or options. All information has been obtained from sources believed to be reliable, but accuracy is not guaranteed. Readers are solely responsible for how they use the information on this website.

Latest trending facts

Copyright © 2026 · Atmosphere Pro on Genesis Framework · WordPress · Log in