The U.S. stock index futures last week hit record highs as their steady, unassuming, low-volatility price uptrends continue. This type of market action is just what the stock market bulls should want to see continue, as it suggests more of the same in the cards for at least the near term. Stay tuned!–Jim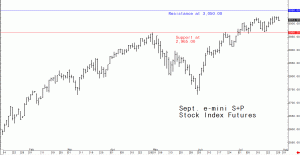
Daily Morning Report
Global Stock Markets Mixed as FOMC Meeting Gets Under Way Tuesday
Tuesday, July 30–Jim Wyckoff’s Morning Markets Report
Asian stocks were mostly firmer and European stocks were mostly weaker overnight. U.S. stock indexes are pointed toward modestly lower openings when the New York day session begins.
A feature in overnight trading was a further decline in the British pound, as the currency fell to a nearly 2.5-year low on worries about a “hard Brexit.” New Prime Minister Boris Johnson is seen as more hard-line on U.K. negotiations with the European Union.
The World Gold Council reported emerging central banks are purchasing gold at a faster pace this summer. Lower government bond yields are attracting more buying interest in the yellow metal.
The main economic event of the week begins on Tuesday when the Federal Reserve’s Open Market Committee (FOMC) meets to determine monetary policy. The Fed is expected to lower interest rates at the conclusion of the meeting Wednesday afternoon.
Then on Friday the U.S. employment situation report for July is out. The key non-farm payrolls number is expected to be up around 165,000. In June, non-farm payrolls were up 224,000.
Also in focus this week is U.S.-China trade talks that have resumed at a high level. U.S. Treasury Secretary Mnuchin and U.S. Trade Representative Lighthizer are in Shanghai for discussions that began today. Expectations are low key for any significant breakthroughs.
The key “outside markets” today see Nymex crude oil prices higher and trading around $57.50 a barrel. The U.S. dollar index is slightly up and today hit another new high for the year overnight.
U.S. economic data due for release Tuesday includes the weekly Goldman Sachs and Johnson Redbook retail sales reports, personal income and outlays, pending home sales, the consumer confidence index and the S&P Corelogic home price index.
–Jim
Quiet Markets Monday but a Busy Trading Week Lies Ahead
Monday, July 29–Jim Wyckoff’s Morning Markets Report
Asian and European stocks mixed to firmer overnight. U.S. stock indexes are pointed toward narrowly mixed openings when the New York day session beings.
Markets are quieter heading into a busy data week in the U.S. On Tuesday the Federal Reserve’s Open Market Committee (FOMC) meets to determine monetary policy. The Fed is expected to raise interest rates at the conclusion of the meeting Wednesday afternoon. Friday the U.S. employment situation report for July is out. The key non-farm payrolls number is expected to be up around 165,000. In June, non-farm payrolls were up 224,000.
Also in focus this week is U.S.-China trade talks that are resuming at a high level. U.S. Treasury Secretary Mnuchin and U.S. Trade Representative Lighthizer are in Shanghai for discussions that began today.
The key “outside markets” today see Nymex crude oil prices near steady and trading around $56.25 a barrel. The U.S. dollar index is slightly up and did poke to a new high for the year overnight.
U.S. economic data due for release Monday is light and includes the Texas manufacturing outlook survey.
–Jim
More Downside Likely for Euro Currency Futures
The Euro currency is one of the most popularly traded futures markets in the world. See on the daily bar chart for the December Euro currency that prices are in a downtrend and have just hit a 16-month low. The bears are in solid technical control and more downside pressure is likely in the near term. Price trends in the currency markets tend to be stronger and longer-lasting than price trends in other markets. Stay tuned!–Jim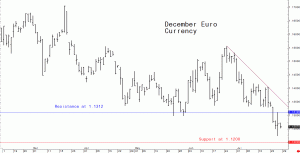
Traders Awaiting U.S. GDP Data Friday Morning
Friday, July 26–Jim Wyckoff’s Morning Markets Report
Asian and European stocks mixed to firmer overnight. U.S. stock indexes are pointed toward higher openings when the New York day session beings.
The U.S. economic highlight of the week is the Friday morning report on second-quarter gross domestic product—the first estimate. The GDP growth rate is seen at up 2.0%, year-on-year. That compares to 3.1% GDP growth in the first quarter of this year. A significant miss on the forecast number would likely move the stock and financial markets.
In other overnight news, an ominous report on very low inflation in the European Union was released Friday, showing the Euro zone inflation will be 1.3% in 2019, 1.4% in 2020 and 1.5% in 2021. That’s according to 52 experts surveyed by the European Central Bank. The ECB wants to see annual inflation of around 2%. The report strongly suggests the ECB will ease its monetary policy soon.
Next week, the U.S. Federal Reserve’s Open Market Committee (FOMC) has its money policy meeting beginning Tuesday, and is expected on Wednesday to ease monetary policy with an interest rate cut at the conclusion of the meeting.
A Commerzbank report today said Chinese demand for gold coming out of Hong Kong is down 83% the past year. Historically Hong Kong has been a major supplier of gold to Chinese consumers. The report mostly blamed the weaker Chinese currency, the yuan, on making gold more expensive to purchase by Chinese consumers.
The key “outside markets” today see Nymex crude oil prices higher and trading around $56.35 a barrel. Meantime, the U.S. dollar index is firmer and is near this year’s high.
U.S. economic data due for release Friday includes the GDP report for the second quarter.
–Jim
World Markets Awaiting ECB Meeting Conclusion Thursday
Asian and European stocks were mostly up overnight. U.S. stock indexes are pointed toward narrowly mixed openings when the New York day session beings. Global equity markets have been boosted recently by notions of easier monetary policies coming soon from the major central banks of the world. Some progress on the U.S.-China trade front this week is also bullish for world stocks.
The European Central Bank is holding its regular monetary policy meeting on Thursday, with results due out soon. Some expect the ECB to lower interest rates today. Next week, the U.S. Federal Reserve’s Open Market Committee (FOMC) has its money policy meeting, and is expected to ease monetary policies at the meeting.
Slowing global economic growth has the central bankers worried. There was another downbeat report coming out of Germany today, as the Ifo business climate index fell in July.
The key “outside markets” today see Nymex crude oil prices higher and trading around $56.50 a barrel. Meantime, the U.S. dollar index is slightly weaker after hitting a five-week high Wednesday.
U.S. economic data due for release Thursday includes the weekly jobless claims report, the advance economic indicators report, durable goods orders, and the Kansas City Federal Reserve manufacturing survey.
–Jim