Corn has been the upside leader in grain prices for several weeks. Corn has begun to rebound but soybeans and wheat have lagged. It’s likely that more gains in corn this week would pull soybean and wheat prices higher, too. Historically, the early-July timeframe is critical for the grain markets, as weather patterns in the U.S. Midwest can change as mid-summer approaches. With the corn and soybeans behind in growth development this year, weather forecasts for the next two to three weeks will produce extra-sensitive reactions from grain traders. Stay tuned!–Jim
Daily Morning Report
Strong U.S. Jobs Report Last Friday Gives Traders Pause
Monday, July 8–Jim Wyckoff’s Morning Markets Report
Asian and European stock markets were mostly weaker in quieter overnight trading. U.S. stock indexes are pointed toward modestly lower openings when the New York day session begins.
Last Friday’s strong U.S. jobs report has somewhat dented trader and investor enthusiasm on notions the Federal Reserve is now less likely to lower interest rates at its July monetary policy meeting. Friday’s jobs data rallied the U.S. dollar and pressured U.S. Treasury prices.
In overnight news, the Turkish lira is under pressure and dropped around 2% against the U.S. dollar after Turkey’s president fired the head of the Turkish central bank.
The key “outside markets” today see Nymex crude oil prices near steady and trading around $57.50 a barrel. Meantime, the U.S. dollar index is slightly down in early U.S. trading.
U.S. economic data due for release Monday is light and includes the employment trends index and consumer credit.
–Jim
Friday’s U.S. Jobs Report to Impact Markets, But Then Likely Quieter Trading
Friday, July 5–Jim Wyckoff’s Morning Markets Report
Asian and European stock markets were mixed in quieter trading overnight. U.S. stock indexes are pointed toward modestly lower openings when the New York day session begins. Look for quieter trading activity in the U.S. after the initial reaction to the U.S. jobs report’s release. Many traders and investors are still celebrating the U.S. Independence Day holiday that was on Thursday.
Traders and investors are awaiting Friday morning’s important June U.S. jobs report from the Labor Department. The key non-farm payrolls number of the report is expected to show a rise of 165,000. However, Wednesday’s weaker ADP number (up 102,000) has many thinking today’s non-farms number will also be a downside miss. A significant downside miss today would likely increase the odds for a Federal Reserve interest rate cut in July.
The key “outside markets” today see Nymex crude oil prices weaker and trading around just below $57.00 a barrel. Meantime, the U.S. dollar index is higher in early U.S. trading.
Other U.S. economic data due for release Friday includes the weekly USDA export sales report.
–Jim
World Bond Yields Continue to Decline
U.S. Treasury bond and note futures prices hit contract highs this week (prices move in an inverse relationship with yields). Meantime, European government bond yield are dropping, with the benchmark German 10-year bund hitting a record low this week. Very low and even problematically low inflation levels in the major economies of the world are perplexing central banks and also the savers around the globe, who get little to no return on the savings accounts. This scenario has been bullish for world stock markets and is likely to become more bullish for raw commodities. Reason: Easing monetary policies of the world’s central banks puts more money into the financial system, which in turn should mean better demand for commodities. Stay tuned!–Jim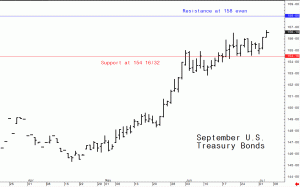
World Government Bond Market Yields Continue to Fall
Wednesday, July 3–Jim Wyckoff’s Morning Markets Report
Asian and European stock markets were mixed overnight. U.S. stock indexes are pointed toward firmer openings when the New York day session begins. Look for trading activity in the U.S. to tail off quickly today, ahead of the U.S. Independence Day holiday on Thursday, when U.S. markets are closed. However, today is a very busy day for U.S. economic data releases.
European stock markets were buoyed by news the International Monetary Fund’s Christine Lagarde has been nominated to be the next president of the European Central Bank. Lagarde is considered a monetary policy dove, like current ECB president Mario Draghi.
Gold prices are sharply higher in early U.S. trading on some safe-haven demand and on ideas of an easier monetary policy coming from the U.S. Federal Reserve. President Trump on Tuesday said he will nominate a couple of likely dovish candidates to serve on the Federal Reserve Board.
The yield on the German 10-year government bond (bund) dropped to another record low Wednesday, at minus 0.394%.
The key “outside markets” today see Nymex crude oil prices modestly up and trading around $56.50 a barrel. Meantime, the U.S. dollar index is slightly higher in early U.S. trading.
Traders and investors are looking ahead to Friday morning’s June U.S. jobs report from the Labor Department. The key non-farm payrolls number of the report is expected to show a rise of 165,000.
U.S. economic data due for release Wednesday includes the weekly MBA mortgage applications survey, the Challenger job-cuts report, the ADP national employment report, the weekly jobless claims report, the international trade report, the U.S. services PMI, the ISM non-manufacturing index, manufacturers’ shipments and orders, the global services PMI, and the weekly DOE liquid energy stocks report.
–Jim
World Marketplace Loses a Bit of Optimism
Tuesday, July 2–Jim Wyckoff’s Morning Markets Report
Asian and European stock markets were mixed to firmer overnight. U.S. stock indexes are pointed toward solidly lower openings when the New York day session begins. Look for trading activity in the U.S. to start to die down today, ahead of the U.S. Independence Day holiday on Thursday.
After having some time to reflect upon the weekend summit meeting on trade between U.S. President Trump and China President Xi, the marketplace is not quite so upbeat on the prospects of a final agreement any time soon. There is speculation now that a deal won’t get done ahead of the 2020 U.S. presidential election. Furthermore, there was some downbeat U.S. manufacturing data released Monday and the Trump administration is again threatening the European Union with trade tariffs.
In overnight news, the Reserve Bank of Australia cut its main interest rate for the second month in a row, and the central bank said more cuts may be needed.
The Euro zone reported its May producer price index dropped 0.1% from April and was up 1.6%, year-on-year. Those numbers were in line with expectations but underscore the low inflation gripping many of the world’s major economies. The yield on the German 10-year government bonds (bunds) hit a new record low today.
There was some civil unrest in the streets of Hong Kong on Monday, but that has fallen out of the TV news cycle, which suggests that situation has calmed down.
The key “outside markets” today see Nymex crude oil prices slightly lower and trading just below $59.00 a barrel. Meantime, the U.S. dollar index is modestly down in early U.S. trading.
U.S. economic data due for release Tuesday includes the weekly Johnson Redbook and Goldman Sachs retail sales report, the ISM New York report on business, the IBD/TIPP economic optimism index, and domestic auto industry sales.
–Jim