The Nymex crude oil futures market dropped to a nearly five-month low to start the month of June. Bears have the firm near-term technical advantage in oil and are now eyeing challenging major psychological support at $50.00 a barrel soon. The accelerating price downtrend suggests more price pressure in crude in the near term. Stay tuned!–Jim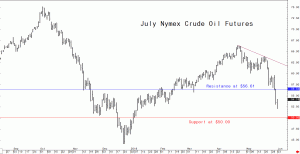
Daily Morning Report
Risk Aversion Keener to Start the Month of June
Monday, June 3–Jim Wyckoff’s Morning Markets Report
European and Asian stock markets were mostly down overnight. U.S. stock indexes are also pointed toward lower openings when the New York day session begins and hit three-month lows overnight.
Risk aversion is keener to start the trading week and the month. The ongoing U.S. trade war with China and new worries about a U.S. trade dispute with Mexico have traders and investors jittery. In fact, some analysts are now saying the Federal Reserve will have to lower U.S. interest rates this year to offset a slowing pace of economic growth caused by the trade disputes.
Gold prices hit a nine-week high overnight on safe-haven demand. Meantime, bond yields in the U.S., Germany and other countries are on the decline as investors seek out safe-haven assets and shed riskier assets like equities.
The European banking sector has been hit especially hard by falling government bond yields that equate to lower interest rates, which in turn hurt banks’ profits. The eight largest banks in the European Union now have a smaller combined market value than JP Morgan, despite the European banks having three times as many assets.
The Euro zone got more downbeat economic news today when the May manufacturing purchasing managers index (PMI) came in at 47.7 versus the forecast for 47.9. Any reading below 50.0 suggests contraction in the sector.
The key “outside markets” today see the U.S. dollar index trading modestly down. Meantime, Nymex crude oil prices are higher and trading around $54.00 a barrel after dropping to a nearly five-month low in overnight trading.
U.S. economic data due for release Monday includes the U.S. manufacturing purchasing managers’ index (PMI), the ISM manufacturing report on business, construction spending, the global manufacturing PMI, and domestic auto industry sales.
–Jim
World Markets Roiled by New U.S. Tariffs Against Mexico
Friday, May 31–Jim Wyckoff’s Morning Markets Report
European and Asian stock markets were mostly down overnight as trader and investor anxiety has up-ticked late this week. U.S. stock indexes are also pointed toward lower openings when the New York day session begins and hit three-month lows overnight.
President Trump late Thursday surprisingly announced new trade tariffs set to go into effect in June against imports from Mexico, in order to persuade that country to help the U.S. battle illegal immigration from the Mexican border with the U.S.
To further rattle the markets, there was more dour economic news coming out of China today. Its manufacturing purchasing managers index (PMI) for May came in at 49.4 versus 50.1 in April and a 49.9 forecast. China’s May services PMI was 54.3, the same as in April and in line with market expectations. A reading below 50.0 suggests contraction in the sector, while a number above suggests growth.
The above news developments underscore a recent theme in the marketplace: increasing concerns regarding slowing global economic growth.
Gold and U.S. Treasury prices are rallying on this last trading day of the week and of the month, on safe-haven demand amid the stock market sell off.
The key “outside markets” today see the U.S. dollar index trading modestly down. Meantime, Nymex crude oil prices are lower, hit a 3.5-month low overnight and are trading around $55.50 a barrel.
U.S. economic data due for release Friday includes personal income and outlays, the ISM Chicago business survey, and the University of Michigan consumer sentiment survey.
–Jim
Government Bond Yields Declining Amid Worries About Slowing Global Economic Growth
The protracted U.S.-China trade war and the resulting concern regarding slowing global economic growth have many world government bond yields down. Wobbly world stock markets recently have also prompted flight-to-quality buying of U.S. and German bonds. Technicals for U.S. Treasury bond and note futures prices remain fully bullish, suggesting more upside price action (lower yields) are likely in the near term. Remember to read my daily reports to get those early clues on potential price trend changes, or price acceleration. Stay tuned!–Jim
World Stock Markets Rebound Thursday
Thursday, May 29–Jim Wyckoff’s Morning Markets Report
European stock markets were mostly up overnight on corrective bounces from recent selling pressure. Asian stocks were mostly down, on continued worries about slowing global economic growth amid the U.S.-China trade war that shows no sign of ending any time soon. U.S. stock indexes are pointed toward firmer openings when the New York day session begins, after hitting 2.5-month lows on Wednesday.
Escalating rhetoric from the U.S. and China suggest diminishing chances the world’s two largest economies will reach any trade agreement before the G-20 meeting in Japan on June 28-29.
The key U.S. economic data point so far this week comes with this morning’s second estimate of first-quarter gross domestic product. GDP is expected to grow 3.0%, year-on-year, versus the last reading of up 3.2%.
The key “outside markets” today see the U.S. dollar index trading near steady following good gains so far this week that have the index trading near its recent two-year high. Meantime, Nymex crude oil prices are slightly higher and trading around $59.00 a barrel. Oil hit a three-month low Wednesday and prices are trending lower on the daily chart.
Other U.S. economic data due for release Thursday include the weekly jobless claims report, preliminary corporate profits, pending home sales, and the weekly DOE liquid energy stocks report.
–Jim
Grain Markets Are on Fire! But for How Long?
Wednesday, May 29–Jim Wyckoff’s Morning Markets Report
World stock markets were mostly down overnight as risk aversion is back on the front burner of the marketplace. The main concern is the prolonged trade war between the U.S. and China (the world’s two largest economies) that sees no end in sight and appears to be escalating. U.S. stock indexes are pointed toward lower openings when the New York day session begins.
Also unnerving European traders is news today Germany’s unemployment rate unexpectedly surged in May, at up 60,000 versus expectations for a decline of 8,000 workers. Germany is the economic workhorse of the European Union.
It’s summertime again and some European Union instability is due. This time, concerns are rising among Europeans as Italy and Greece are balking about conforming to EU rules on fiscal discipline. And the U.K. can’t seem to figure out how to leave the EU in a smooth fashion.
A feature in the markets this week is falling government bond yields, partly due to “flight-to-safety” buying amid keener risk avoidance among traders and investors. More and more market watchers are thinking the long bull run in equities has ended. Germany today sold a five-year debt instrument today at a record low yield of -0.56%.
The key “outside markets” today see the U.S. dollar index trading slightly higher following good gains Tuesday, while Nymex crude oil prices are solidly lower and trading just below $58.00 a barrel.
U.S. economic data due for release Wednesday includes the weekly MBA mortgage applications survey, weekly Goldman Sachs and Johnson Redbook retail sales data, and the Richmond Fed business survey.
–Jim