• Skip to main content
  • Skip to footer

Jim Wyckoff

Dominate Your Market

  • Daily Morning Report
  • Meet Jim
    • Testimonials
  • Contact Jim
  • Sample Reports and Charts
  • FAQ
  • Jim’s educational e-books

Daily Morning Report

U.S. stocks rebound Friday, but risk aversion still keener

June 12, 2020 by Jim Wyckoff

Friday, June 12–Jim Wyckoff’s Morning Markets Report

Global stock markets were mixed in overnight trading, with Asian stocks mostly down and European stocks mostly up. U.S. stock indexes are pointed toward solidly higher openings when the New York day session begins, but the overnight gains are only about one-third of Thursday’s very sharp losses. Risk aversion has returned to the marketplace late this week, on a surge in Covid-19 cases in some major global economies after they started to reopen businesses, which in turn increased human interaction. It could be that the rise is due to more testing that is prompting more cases to be reported. Traders and investors also got a reminder from the Federal Reserve this week of just how bad is the U.S. and global economic situation at present, and the tough road ahead. President Trump on Thursday criticized the Fed for being too dour in its predictions.

U.S. Treasury Secretary Mnuchin on Thursday said the government is mulling a second round of cash payments to American taxpayers who qualify.

In overnight news, the U.K. reported its economy contracted by 20.4% in April. Meantime, Euro zone industrial output for April was reported down 17.1% from March and down 28% year-on-year—for the largest drop ever recorded.

The important outside markets early today see the U.S. dollar index slightly weaker. The greenback is in a steep downtrend and the USDX hit a three-month low this week. Meantime, Nymex crude oil prices are slightly up and trading around $36.50 a barrel. The yield on the benchmark U.S. Treasury 10-year note is currently around the 0.7% level.

U.S. economic data due for release Friday includes import and export prices and the University of Michigan consumer sentiment survey.

–Jim
Continue Reading
Filed Under: Blog News, Jim's Morning Report, Uncategorized

Bullish longer-term prospects for raw commodity sector

June 11, 2020 by Jim Wyckoff

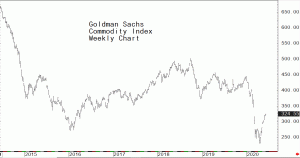
A potential “green shoot” for the raw commodities markets is a bullish technical signal coming from the Goldman Sachs Commodity Index (GSCI), which is a basket of several major commodity futures markets rolled into one composite price index. The weekly GCSI chart shows prices in April careened to a 17-year low, including producing big gaps down on the bar chart in March. However, in May price action on the weekly chart reversed course, including producing a big gap to the upside. The price action in April and May created a very significantly bullish “island bottom” reversal pattern, to strongly suggest a major low is in place for the GSCI, and that prices are now likely to trend higher in the coming weeks and months, or even longer.–Stay tuned! Jim

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Wake-up call from Federal Reserve dents risk appetite

June 11, 2020 by Jim Wyckoff

Thursday, June 11–Jim Wyckoff’s Morning Markets Report

Global stock markets were mostly lower in overnight trading. U.S. stock indexes are pointed toward solidly lower openings when the New York day session begins. Risk aversion has returned to the marketplace following a wake-up call delivered by the Federal Reserve following its two-day FOMC meeting Wednesday afternoon. The Fed made no changes in U.S. monetary policy but leaned dovish, saying the U.S. economy could take years to fully recover from its recent damage inflicted by the Covid-19 pandemic. The central bank also painted a bleak picture of the present state of the U.S. economy, including forecasting U.S. GDP at minus 6.5% this year and unemployment above 9% by the end of the year. Those numbers were not a shock to the marketplace, but a grim reminder to traders and investors who had just pushed the Nasdaq stock index to a new record high Wednesday morning and the S&P 500 to a three-month high Monday.

Said one market analyst in an email dispatch Thursday morning: “The Fed is now committed to keeping interest rates near zero until at least the end of 2022 and using all its tools to support the economy. This could translate into further speculative bets and push the rally in equities and corporate debt higher. However, without real economic recovery the market will have to deal with a more significant challenge, which is debt insolvency. That’s why the disconnect between asset performance and economic fundamentals cannot run forever and investors will need to become more rational with their investment approach.”

There are also growing worries in the global marketplace about a “second wave” of the Covid-19 pandemic hitting many countries. There is some evidence such may be occurring in some regions of some countries, including the U.S.

The important outside markets see the U.S. dollar index firmer on a bounce after hitting a three-month low Wednesday. The greenback is in a serious swoon. Meantime, Nymex crude oil prices are lower on a corrective pullback after hitting a three-month high above $40.00 Monday, and are trading around $38.50 a barrel. The yield on the benchmark U.S. Treasury 10-year note is currently around the 0.7% level. Gold is solidly up Thursday morning and bulls are having a good week as safe-haven demand has returned to the marketplace.

U.S. economic data due for release Thursday includes the weekly jobless claims report and the producer price index. Jobless claims in the latest reporting week are seen up 1.6 million.

–Jim
Continue Reading

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Risk appetite remains upbeat at mid-week; FOMC meeting conclusion awaited

June 10, 2020 by Jim Wyckoff

Wednesday, June 10–Jim Wyckoff’s Morning Markets Report

Global stock markets were mostly weaker in overnight trading. U.S. stock indexes are pointed toward narrowly mixed openings when the New York day session begins. The Nasdaq index overnight hit another record high, while the S&P 500 stock index on Monday hit a three-month high. Risk appetite remains generally upbeat at mid-week as businesses in major economies continue to open back up after the Covid-19 lockdown and social distancing guidelines are relaxed.

Today concludes the two-day meeting of the Federal Reserve’s Open Market Committee (FOMC) that will see an afternoon statement, along with a press conference from Fed Chairman Jay Powell. No change in interest rates is expected. However, the Fed’s economic projections and Powell’s remarks will be closely scrutinized and will probably move markets to some degree.

In overnight news, the OECD think tank forecast global economic growth will fall 6% this year, if a second wave of Covid-19 can be avoided. The OECD also said the world economy “is on a tightrope” and a second wave of the pandemic would be a terrible blow to the world economy.

China got some dour economic news at mid-week as it reported its industrial prices in May fell by 3.7%, year-on-year. Consumer inflation fell to a 2.4% growth rate. Both figures undershot market expectations.

The important outside markets see the U.S. dollar index slightly lower and hitting a three-month low overnight. The greenback is in a serious swoon. Meantime, Nymex crude oil prices are lower on a corrective pullback after hitting a three-month high above $40.00 Monday, and is trading around $38.00 a barrel. The yield on the benchmark U.S. Treasury 10-year note is currently around the 0.79% level.

U.S. economic data due for release Wednesday includes the weekly MBA mortgage applications survey, the consumer price index, real earnings and the weekly DOE liquid energy stocks report.

–Jim
Continue Reading

Filed Under: Blog News, Jim's Morning Report, Uncategorized

U.S. stock index bulls power prices higher

June 9, 2020 by Jim Wyckoff

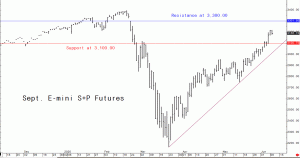
“The trend is your friend” is the tried and true market adage that so many professional traders espouse. The U.S. stock indexes are trending solidly up and there are no early clues to suggest that market tops are in place. Any early, bearish chart clues that do arise you will hear from me first, via my daily markets update report.–Stay tuned! Jim

Filed Under: Blog News, Jim's Morning Report, Uncategorized

Stock indexes see normal, corrective pullbacks Tuesday

June 9, 2020 by Jim Wyckoff

Tuesday, June 9–Jim Wyckoff’s Morning Markets Report

Global stock markets were mixed but mostly weaker in overnight trading. U.S. stock indexes are pointed toward lower openings when the New York day session begins, on normal corrective pullbacks from recent strong gains. The Nasdaq index overnight hit a record high, while the S&P 500 stock index hit a three-month high Monday. Trader and investor risk sentiment remains upbeat. The just-released NFIB small business optimism index rose to 94.4 in May from 90.9 in April. The U.S. government reported the American economy officially entered recession in February, while also on Monday the Federal Reserve expanded its lending program to U.S. businesses.

In overnight news, the Euro zone economy in the first quarter contracted by 3.6% from the fourth quarter of last year. Forecasters expect the second-quarter GDP reading to be worse.

The World Bank has forecast global GDP to see a 5.2% contraction this year. Advanced economies will contract 7%, led by a 9.1% decline in the Euro zone. Other GDP projections see the U.S. at -6.1%, China at up 1.0% and India -3.2%. “This is the first recession since 1870 triggered solely by a pandemic, and it continues to manifest itself… Given this uncertainty, further downgrades to the outlook are very likely,” the World Bank said. Global economic growth is due for a rebound in 2021, growing 4.2%, said the World Bank.

Today begins the two-day meeting of the Federal Reserve’s Open Market Committee (FOMC) that ends Wednesday afternoon with a statement and press conference from Fed Chairman Jay Powell.

The important outside markets see the U.S. dollar index slightly higher early today on a corrective bounce from its recent 11-week low. Meantime, Nymex crude oil prices are lower on a corrective pullback after hitting a three-month high Monday, and trading around $37.25 a barrel. The yield on the benchmark U.S. Treasury 10-year note is currently around the 0.82% level.

U.S. economic data due for release Tuesday includes the weekly Goldman Sachs and Johnson Redbook retail sales reports, the NFIB small business index, the IBD/TIPP economic optimism index, and monthly wholesale trade.

–Jim
Continue Reading

Filed Under: Blog News, Jim's Morning Report, Uncategorized

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 238
  • Page 239
  • Page 240
  • Page 241
  • Page 242
  • Interim pages omitted …
  • Page 424
  • Go to Next Page »

Footer

Disclaimer

There is a risk of financial loss in futures and options trading. Futures trading is neither easy nor an easy way to make money. It takes hard work to have success. Please use sound money management when trading futures. Past performance is not necessarily indicative of future results. Nothing on this website is intended to be a trading recommendation to buy or sell futures or options. All information has been obtained from sources believed to be reliable, but accuracy is not guaranteed. Readers are solely responsible for how they use the information on this website.

Latest trending facts

Copyright © 2026 · Atmosphere Pro on Genesis Framework · WordPress · Log in