The U.S. stock indexes have made strong rebounds from the sharp declines seen during October, to produce bullish V-Bottom reversal patterns. The S&P and Nasdaq bulls have good upside technical momentum, but prices are still well below the September highs. Even with the solid rebound in the U.S. stock indexes the past two weeks, bulls still have heavy lifting to do in the near term to suggest the September highs can be challenged or taken out on the upside. Stay tuned!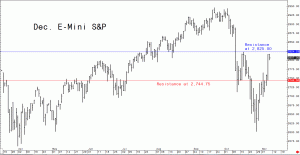
Daily Morning Report
Risk Attitudes Upbeat Following U.S. Mid-Term Elections
Thursday, November 8–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
European stock markets were mixed overnight, while Asian shares were mostly firmer. U.S. stock indexes are pointed toward lower openings when the New York day session begins, on a corrective pullback from Wednesday’s solid gains.
Risk appetite in the world marketplace is mostly upbeat following the U.S. mid-term elections that produced a divided Congress.
In overnight news, upbeat economic data out of China defied expectations that its trade war with the U.S. is crimping its economy. China’s exports in October rose by 15.6%, year-on-year. That handily beat expectations of an 11% increase. Imports in October were up 21.4%, year-on-year. Imports from the U.S. dropped 1.8%. This data suggests China could be in no hurry to settle its trade dispute with the U.S. However, as has been the case for years, some do question the veracity of China’s economic numbers.
Meantime, economic data out of the European Union showed the Euro zone’s 2018 economic growth is seen at 2.1%, with 2019 GDP seen at 1.9% and then at 1.7% in 2020. The report estimates 2018 and 2019 inflation for the Euro zone at an annual rate of 1.8%.
Focus today is on the conclusion of the Federal Reserve’s Open Market Committee (FOMC) meeting that began Wednesday morning and ends with a statement Thursday afternoon. No change in U.S. interest rates is expected. As always, traders will scrutinize wording of the FOMC statement and Chairman Jay Powell’s remarks at his press conference, for clues on the future direction and timing of U.S. monetary policy.
The key “outside markets” today find the U.S. dollar index higher on a rebound from selling pressure seen this week. Meantime, Nymex crude oil prices are slightly higher and trading just below $62.00 a barrel. Nymex oil prices this week hit a seven-month low.
Other U.S. economic data due for release Thursday includes the weekly jobless claims report and the monthly chain store sales index.
–Jim
Marketplace Appears to Embrace a Split U.S. Congress, Following Elections
Wednesday, November 7–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to firmer overnight, with European shares mostly up and Asian shares narrowly mixed. U.S. stock indexes are pointed toward solidly higher openings when the New York day session begins.
Tuesday’s U.S. mid-term elections turned out as many had expected and saw the Republicans maintain control of the Senate but the Democrats gained control of the House of Representatives. The world marketplace appears comfortable with a split U.S. Congress and likely gridlock on major new legislation over the next two years.
Many believed the U.S. elections were a referendum on the performance of President Trump. Many would argue the U.S. elections did not turn out too bad for Trump, noting that history shows the party not in control typically fares better in mid-term elections.
The U.S. dollar is taking a hit following the elections. There are now notions any new Trump fiscal policy proposals that would be pro-growth and pro-business will get mired down in Congress and die.
Today the Federal Reserve’s Open Market Committee (FOMC) meets for a two-day meeting to discuss U.S. monetary policy, with a statement due Thursday afternoon. No change in interest rates is expected at this meeting. As always, traders will scrutinize wording of the FOMC statement and Chairman Jay Powell’s remarks at his press conference, for clues on the future direction and timing of U.S. monetary policy.
The other key “outside market” today finds Nymex crude oil prices higher and trading around $62.50 a barrel.
U.S. economic data due for release Wednesday includes the weekly MBA mortgage applications survey, the weekly DOE liquid energy stocks report and consumer installment credit.
–Jim
Soybean Bulls Gain Some Momentum, But Need to Show More Power to Suggest Uptrend Can Be Sustained
The soybean market has seen a solid price rebound recently, to suggest a harvest low was put in place in September. The bulls have more work to do to suggest a price utprend can be sustained. A move in January soybean futures above stiff chart resistance at the October high of $9.06 1/4 would provide the bulls with the power to then suggest prices could trend sideways to higher into the end of the year. Stay tuned!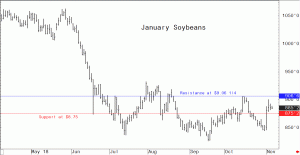
World Marketplace Quieter, Awaiting U.S. Mid-Term Election Results
Tuesday, November 6–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to weaker overnight. U.S. stock indexes are pointed toward slightly lower openings when the New York day session begins.
Focus of the world marketplace is on today’s U.S. mid-term elections, which many believe are a referendum on the performance of President Trump. Big gains by the Democrats would likely be bearish for the U.S. stock market and would signal gridlock in Congress the next two years.
In overnight news, the European Union reported a hotter reading on its inflation today. The Euro zone September producer price index came in at up 0.5% from August and up 4.5%, year-on-year.
On Wednesday and Thursday the Federal Reserve’s Open Market Committee (FOMC) meets to discuss U.S. monetary policy, with a statement due Thursday afternoon. No change in interest rates is expected at this meeting.
The key outside markets today see the U.S. dollar index slightly higher. Meantime, December Nymex crude oil prices are slightly weaker and trading just below $63.00 a barrel.
U.S. economic data due for release Tuesday includes the weekly Goldman Sachs and Johnson Redbook retail sales reports, and the global services PMI.
–Jim
Busy Trading Week Lies Ahead, Including U.S. Mid-Term Elections
Monday, November 5–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed overnight, with European shares mostly firmer and Asian shares mostly weaker. U.S. stock indexes are pointed toward narrowly mixed openings when the New York day session begins.
Expectations for a U.S.-China trade deal have been ratcheted down early this week, following some positive signs on the matter late last week. President Trump late last week sounded upbeat on a deal being reached soon with China. However, Trump’s chief economic advisor Larry Kudlow then downplayed any imminent breakthrough on the U.S.-China trade war.
In another sign that China’s economy is being significantly impacted by the trade war with the U.S., a report over the weekend showed China’s service sector slowed to a 13-month low.
Focus in the U.S. is on Tuesday’s mid-term elections, which many believe will be a referendum on the performance of President Trump. Gains by the Democrats would likely be bearish for the U.S. stock market.