The December e-mini S&P stock index futures are in a steep downtrend on the daily bar chart, after hitting a six-month low last Friday. The bulls will be happy to see the calendar turn to November, after the historically turbulent month of October delivered another nasty blow to the U.S. stock market. Bulls are still in serious near-term technical trouble, to suggest sideways-at-best trading in the near term, if not new lows carved out. Stay tuned!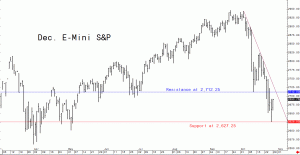
Daily Morning Report
Global Stock Markets Mostly Up Monday, Except China
Monday, October 29–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to mostly firmer overnight. U.S. stock indexes are pointed toward higher openings when the New York day session begins. European stock indexes were mostly up, following news that the S&P Global Ratings agency on Friday did not downgrade Italy’s debt rating. China’s stock market suffered more losses Monday amid investor worries about the world’s second-largest economy.
U.S. stock indexes on Friday fell to six-month lows before posting rebounds on the day. Stock market bulls will be glad to get the historically turbulent month of October out of the say and hopefully get a “Santa Claus rally” this year.
In overnight news, German Chancellor Angela Merkel has announced she will step down as leader of her Christian Democratic party after disappointing election results. Europe market watchers say that’s a sign of Merkel’s decline in power in Germany and in the European Union.
The key outside markets today find the U.S. dollar index higher and hovering near Friday’s nine-week high. Meantime, November Nymex crude oil prices are weaker and trading around $67.50 a barrel.
The key U.S. economic data point of the week, if not the month, will be Friday’s November employment report from the Labor Department.
U.S. economic data due for release Monday includes personal income and outlays and the Texas manufacturing outlook survey.
–Jim
Buckle Up! It’s Likely to Be a Volatile Trading Day Friday
Friday, October 26–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mostly lower overnight. U.S. stock indexes are pointed toward sharply lower openings and at five-month lows when the New York day session begins. It’s likely going to be another volatile day during the U.S. trading session today. Disappointing earnings reports from Amazon and Alphabet stocks are helping to press the U.S. equities lower.
There are near-term technical clues the U.S. stock indexes have put in near-term market tops, if not major tops. If that’s indeed the case, it’s a bullish element for hard assets like the precious metals and other raw commodities. Today will be an extra important trading day for U.S. stock indexes. Solid losses to end the week will further exacerbate trader and investor anxiety heading into an uncertain weekend. A big rally in U.S. stocks today would assuage the marketplace anxiety to some degree.
Traders and investor can point to no single factor that is spooking the world marketplace in late October. There are ongoing geopolitical concerns that include the U.S.-China trade war, U.S.-Saudi Arabia tensions over the murdered Saudi journalist, and Italy’s defiance over forming its budget to meet European Union rules. It’s not going to be surprising to see some fresh news on one of these fronts in the next few days.
The Chinese yuan fell to a multi-year low versus the U.S. dollar overnight. The U.S. is worried China is devaluing its currency to gain trade advantages.
In other overnight news, the European Union got more dour economic news today when the European Central Bank’s survey of professional forecasters reported weaker economic projections for the Euro zone in the coming years. The survey projected a 2.0% GDP gain this year and 1.8% growth in 2019.
The U.S. economic highlight this week will be the first estimate of third-quarter GDP due out Friday morning. GDP is seen up 3.4% in the third quarter, on an annual basis. The marketplace could react to the GDP data if it’s a miss from forecasts. But it appears the cards are stacked against the stock market bulls because a GDP miss to the downside would mean slowing business activity, while a miss to the upside would mean the Federal Reserve likely continuing to tighten monetary policy.
The key outside markets today find the U.S. dollar index near steady and hovering near this week’s nine-week high. Look for the greenback to remain supported on safe-haven demand amid wobbly world stock markets. Meantime, November Nymex crude oil prices are lower and trading around $66.50 a barrel. Oil prices fell to a two-month low earlier this week, on worries about slowing world economic growth, due in part to the U.S.-China trade war.
Other U.S. economic data due for release Friday includes the University of Michigan consumer sentiment survey.
–Jim
U.S. Treasuries Gain on Safe-Haven Demand, But…
The turmoil in world stock and financial markets recently has boosted safe-haven U.S. Treasuries. T-Bond and T-Note futures this week have seen downtrend lines on the daily bar charts negated. See on the daily chart for December T-Bonds that a fledgling uptrend line is in place. As long as trader and investor anxiety in the world marketplace remains elevated, U.S. Treasury prices will be supported. However, once the world marketplace settles down and risk aversion recedes, look for selling pressure in U.S. bonds and notes to resume. Stay tuned!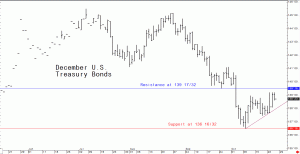
Asian Stock Markets Down Thursday, and Into Bear Market Territory
Thursday, October 25–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to lower overnight, following the strong losses in U.S. stock indexes Wednesday that put those indexes into negative territory for this year. Asian stock markets were mostly lower overnight. China’s and South Korea’s stock markets are now in bear market territory, having dropped over 20% from their bull market highs. U.S. stock indexes are pointed toward higher openings when the New York day session begins. Look for another volatile day in the U.S. markets.
There are near-term technical clues the U.S. stock indexes have put in near-term market tops, if not major tops.
Traders and investor can point to no one element that is spooking the world market place at present. There are geopolitical issues that include the U.S.-China trade war, U.S.-Saudi Arabia tensions over the murdered Saudi journalist, and Italy’s defiance over forming its budget to meet European Union rules. And there is creeping inflation in the world economies at present. Most don’t deem the inflation rates problematic, yet. However, there is a new generation of worldwide investors that have ostensibly never experienced inflation. So a 3% inflation rate could be spooking them.
Traders and investors in Europe are awaiting Thursday’s European Central Bank regular monetary policy meeting. No change in EU monetary policy is expected, but ECB chief Mario Draghi’s press conference could provide clues on future moves by the central bank. Also, Draghi could comment on the rift between Italy’s new government and the EU.
The U.S. economic highlight this week will be the first estimate of third-quarter GDP due out Friday morning. GDP is seen up 3.4% in the third quarter, on an annual basis.
The key outside markets today find the U.S. dollar index weaker on a normal corrective pullback after hitting a nine-week high on Wednesday. Meantime, November Nymex crude oil prices are slightly weaker and trading just below $67.00 a barrel. Oil prices fell to a two-month low on Tuesday.
U.S. economic data due for release Thursday includes the weekly jobless claims report, durable goods orders, advance economic indicators, and the Kansas City Fed manufacturing survey.
–Jim
World Markets Calm Down a Bit at Mid-Week
Wednesday, October 24–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to firmer overnight, rebounding from solid losses Tuesday, as risk aversion is a bit less today than it was on Tuesday. U.S. stock indexes are pointed toward lower openings when the New York day session begins.
The S&P 500 stock index on Tuesday dropped below what was strong chart support at its October low. Such suggests a new leg down in prices is coming for the U.S. stock market. That’s bullish for hard assets such as gold and silver.
There are still geopolitical issues looming over the world marketplace, including the U.S.-China trade war, U.S.-Saudi Arabia tensions over the murdered Saudi journalist, and Italy’s recalcitrance over forming its budget to meet European Union constricts. The EU Wednesday rejected the latest Italian draft budget.
All of the above have pushed world stock markets and crude oil prices sharply lower, as well as rallied safe-haven assets like gold, U.S. Treasuries and the U.S. dollar.
In overnight news, the Euro zone got some dour economic data when the composite Markit purchasing managers index (PMI) fell to 52.7 in October from 54.1 in September. The October number was lower than expected and the lowest level in two years.
Traders and investors in Europe are awaiting Thursday’s European Central Bank regular monetary policy meeting. No change in EU monetary policy is expected, but ECB chief Mario Draghi’s press conference could provide clues on future moves by the central bank. Also, Draghi could comment on the rift between Italy’s new government and the EU.
The U.S. economic highlight this week will be the first estimate of third-quarter GDP due out Friday morning. GDP is seen up 3.4% in the third quarter, on an annual basis.