The gold market saw good price gains on Thursday as the U.S. dollar index sold off sharply. The yellow metal bulls did regain some technical momentum on the rally, but need to show more power soon to suggest a price uptrend can be sustained. It’s likely going to take some geopolitical tensions heating up to significantly boost the gold market–and that is entirely possible. Stay tuned!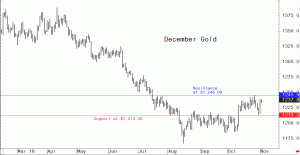
Daily Morning Report
World Stock Markets Rally on Hopes for U.S.-China Trade Deal
Friday, November 2–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mostly higher overnight. U.S. stock indexes are pointed toward higher openings when the New York day session begins. Trader and investor attitudes are upbeat amid recent proclamations by U.S. President Trump and Chinese President Xi Jinping that suggest the world’s two largest economies are coming closer together to at least formal negotiations on trade. Trump late Thursday tweeted he had a “long and very good” conversation with Xi. Other reports said Trump has asked his advisors to draw up a trade agreement with China. This is the most positive rhetoric coming from both sides in months.
The Chinese yuan also gained against the U.S. dollar on the China-U.S. trade developments.
Focus in the U.S. is turning to next week’s mid-term elections, which many believe will be a referendum on the performance of President Trump. Gains by the Democrats would likely be bearish for the U.S. stock market.
The key outside markets today see the U.S. dollar index lower again following solid losses Thursday. The USDX is seeing a normal corrective pullback after hitting a 16-month high on Wednesday. Meantime, December Nymex crude oil prices are slightly weaker after hitting a 4.5-month low on Thursday, and are presently trading around $63.50 a barrel.
The key U.S. economic data point of the week, if not the month, will be Friday morning’s November employment report from the Labor Department. The key non-farm payrolls number is forecast to come in at up 188,000. However, Wednesday’s ADP national employment report reading of up 227,000 suggests Friday’s jobs report could be stronger than forecast.
Other U.S. economic data due for release Friday includes the international trade report, manufacturers’ shipments and inventories and the global manufacturing purchasing managers index.
–Jim
Stock Markets Rally As Marketplace Glad Calendar Turns To November
Thursday, November 1–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mostly higher overnight. U.S. stock indexes are pointed toward higher openings when the New York day session begins, on an extension of a strong rebound from Monday’s sell-off that drove the indexes to six-month lows. Stock market traders and investors are glad to have the historically turbulent month of October out of the way and are now hoping for a seasonal Santa Claus rally. However, those thinking the world stock markets have seen the “all clear” siren as the calendar turns to November are likely going to be disappointed.
Focus in the U.S. is turning to next week’s mid-term elections, which many believe will be a referendum on the performance of President Trump.
The key outside markets today find the U.S. dollar index solidly lower on a downside correction from recent strong gains that pushed the index to a 16-month high on Wednesday. Meantime, December Nymex crude oil prices are weaker, hit a nine-week low overnight and are trading just below $65.00 a barrel. Recent technical damage on the charts suggests more downside for crude oil in the near term.
The key U.S. economic data point of the week, if not the month, will be Friday’s November employment report from the Labor Department. The key non-farm payrolls number is forecast to come in at up 188,000. However, Wednesday’s ADP national employment report reading of up 227,000 suggests Friday’s jobs report could be stronger than forecast.
U.S. economic data due for release Thursday includes the weekly jobless claims report, the Challenger job-cuts report, preliminary productivity and costs, the U.S. manufacturing purchasing managers index, construction spending and the ISM manufacturing report on business.
–Jim
Greenback Bulls Flexing their Muscles on World FOREX Market
The U.S. dollar index is a basket of six major world currencies weighted against the greenback. See on the daily bar chart for the USDX that prices this week have powered to a multi-month high. The dollar is seeing appreciation from a strong U.S. economy and on safe-haven demand amid wobbly world stock markets. Remember that trends in the currency markets tend to be stronger and longer-lasting that price trends in other markets. Thus, the dollar could continue to gain in the coming weeks, or longer. Stay tuned!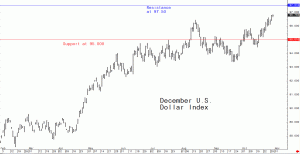
U.S. Stock Market Trying to Recover, But Chart Damage Remains
Wednesday, October 31–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to mostly higher overnight. U.S. stock indexes are pointed toward higher openings when the New York day session begins. There is still strong near-term technical evidence the U.S. stock indexes have put in market tops. Volatility in the U.S. stock market could still appear at any time, as seen with Monday afternoon’s price swoon.
Today is the last trading day of the month, which makes it a more important trading day, from a technical chart perspective.
China’s official purchasing managers’ index also fell to 50.2 in October from 50.8 in September. The October number is the lowest in two years. A reading below 50.0 suggests contraction in the sector.
The Chinese yuan has dropped to a 10-year low against the U.S. dollar this week. There is a debate on whether the Chinese government wants the yuan to depreciate to gain world trade advantages. Or, the government may want to stem the yuan’s slide due to fears of capital flight out of China.
In another sign of the stark divergence between the U.S. and European Union economies, the Euro zone reported its unemployment rate for October today, at 8.1%. The U.S. rate is 3.7%. Meantime, the Euro zone inflation rate rose to a nearly six-year high of 2.2%, basis its latest consumer price index report for October issued today.
Global Stock Markets Still Jittery Tuesday After U.S. Sell-Off Monday
Tuesday, October 30–Jim Wyckoff’s Morning Markets Report
OVERNIGHT DEVELOPMENTS
Global stock markets were mixed to mostly lower overnight. U.S. stock indexes are pointed toward higher openings when the New York day session begins, on an upside correction following Monday’s sell off that pushed the indexes to six-month lows. There is still strong near-term technical evidence the U.S. stock indexes have put in market tops.
Reports Monday afternoon said the Trump administration will impose tariffs on all Chinese goods imported into the U.S., if the meeting between Presidents Trump and Xi Jinpin in Argentina in late November do not produce results. This news helped sink the U.S. stock market Monday afternoon.
In overnight news, the Euro zone reported its latest quarterly gross domestic product rose only a paltry 0.6% in the third quarter, year-on-year. That compares to the latest U.S. GDP third-quarter growth rate of 3.5%.
The key outside markets today find the U.S. dollar index higher and setting a new for-the-move high overnight. Meantime, November Nymex crude oil prices are lower and trading around $66.50 a barrel.
The key U.S. economic data point of the week, if not the month, will be Friday’s November employment report from the Labor Department.
U.S. economic data due for release Tuesday includes the weekly Goldman Sachs and Johnson Redbook retail sales reports, the S&P/Case-Shiller home price indexes, and the consumer confidence index.
–Jim